Newnan & Sharpsburg
You Don't Need 20% Down to Buy in Newnan or Sharpsburg: A First-Time Buyer's Guide
By the Sharpsburg Realty Experts Media Team
Demo content: not for publication. The agent interviews, agent profiles, client stories, transactions and client reviews in this test article are fictional demo records. Every quotation from our agent and the buyer story below are fictional demo content, not real testimony or real sales. The down-payment research and program details cited are real and linked to their sources.
$80,000.
That's 20% down on a $400,000 home, and for plenty of renters in Newnan and Sharpsburg, it's the number that ends the conversation before it starts. Somebody in the family said you need 20%, so homeownership goes on the someday list.
That number isn't a rule. To sort out what is required, our media team dug into the latest national down-payment data and the loan and assistance programs available to Georgia buyers. We also sat down with Caleb Brooks, a buyer specialist on our team, to talk through how a first-time buyer should actually plan.
His short version: know your choices.
Do I really need 20% down?
No. Most buyers don't put down that much, and some loan programs allow far less for buyers who qualify.
When we asked Caleb what first-time buyers misunderstand, his answer was simple: "Mostly that it's a universal rule. It isn't." He added, "Some buyers may qualify for loans that allow less." Your lender, not your agent, decides what you qualify for.
The national numbers back him up:
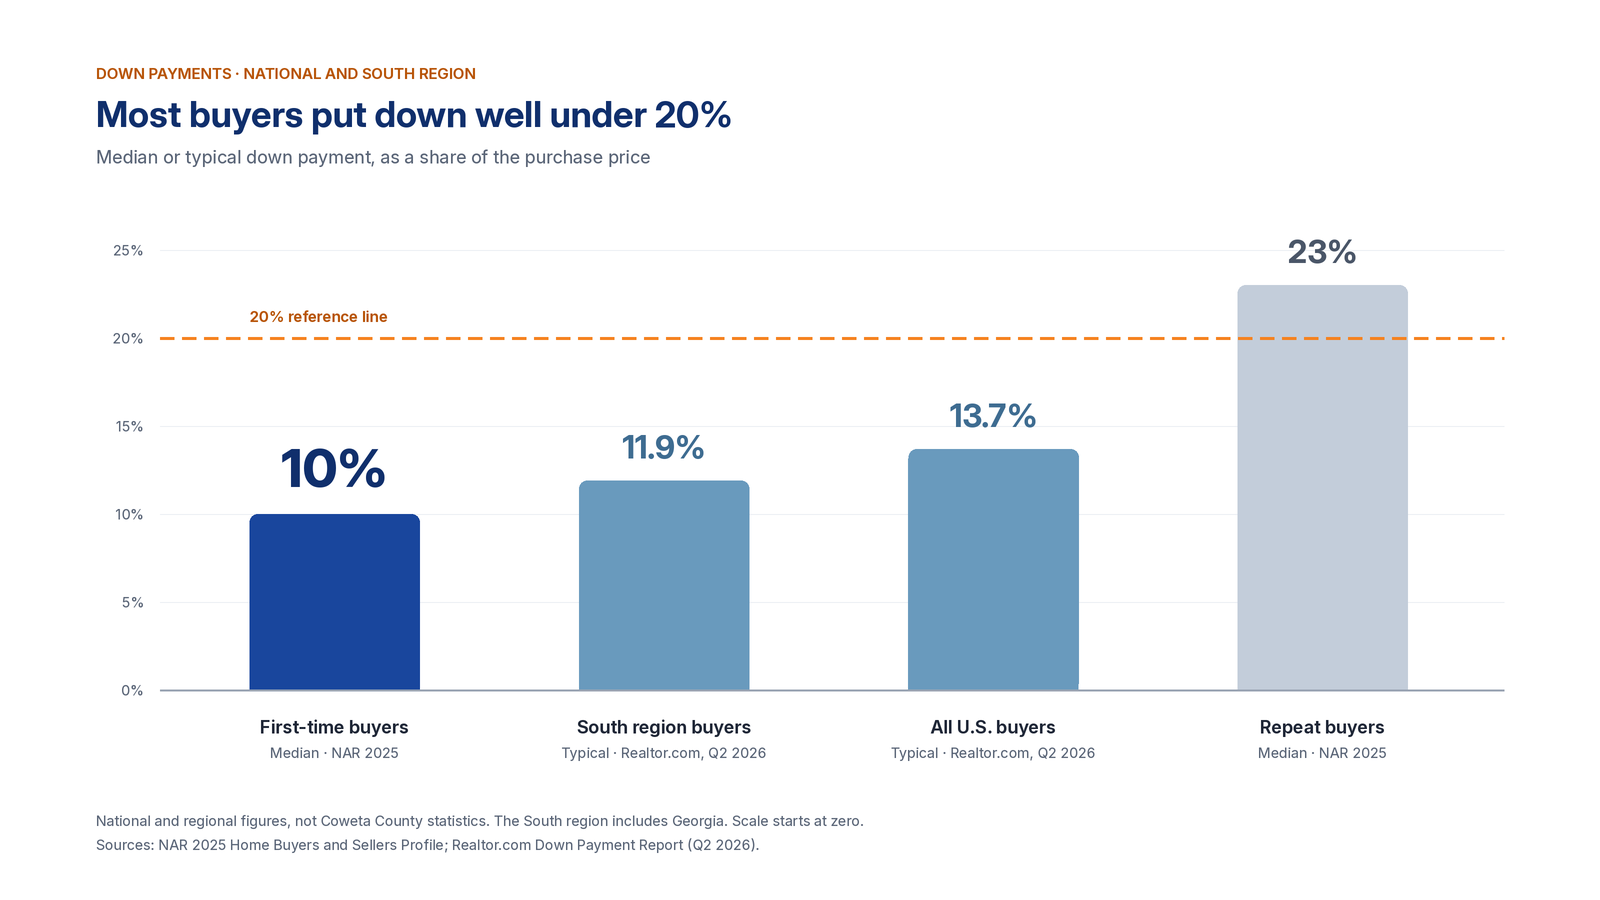
- All U.S. buyers: the typical down payment was 13.7% of the purchase price in the second quarter of 2026, and the median down payment was $27,100, according to Realtor.com's latest down-payment report. In the South, which includes Georgia, buyers typically put down 11.9%.
- First-time buyers: the median down payment was 10%, according to NAR's 2025 buyer profile. That's actually the highest level since 1989. Repeat buyers put down a median of 23%.
And the program minimums are lower still. Fannie Mae's 97% loan-to-value options and its HomeReady loan allow as little as 3% down. FHA loans, as listed in Georgia Dream's program matrix, go to 96.5% loan-to-value, or 3.5% down.
These are national and regional figures, not Coweta County statistics. As Caleb put it: "The national studies can show that plenty of people put down less than 20%, but they don't tell you what one particular Coweta County family should do."
What's the difference between my down payment and what I need to close?
Quite a bit, and it's the part first-time buyers most often miss.
Caleb starts every budget conversation the same way. "I try to separate three numbers: the down payment, the full amount they'll need to close, and the payment they'll need to manage each month after moving in."
Here's how the down payment alone plays out on a $400,000 home, a price that sits within the range of recent local medians. Over the three months ending in September, Redfin put the median sale price at about $358,000 in ZIP 30263, $390,000 in 30265 and $485,000 in Sharpsburg's 30277. Countywide, Coweta's September median was $412,200, according to Georgia MLS.
| Down payment | Amount on a $400,000 home |
|---|---|
| 3% | $12,000 |
| 3.5% | $14,000 |
| 5% | $20,000 |
| 10% | $40,000 |
| 20% | $80,000 |
"But those amounts aren't complete cash-to-close estimates," Caleb said. On top of the down payment come the inspection, the appraisal, closing costs, prepaid taxes and insurance, and possibly HOA charges. Then you need money left over after closing for repairs and everyday life.
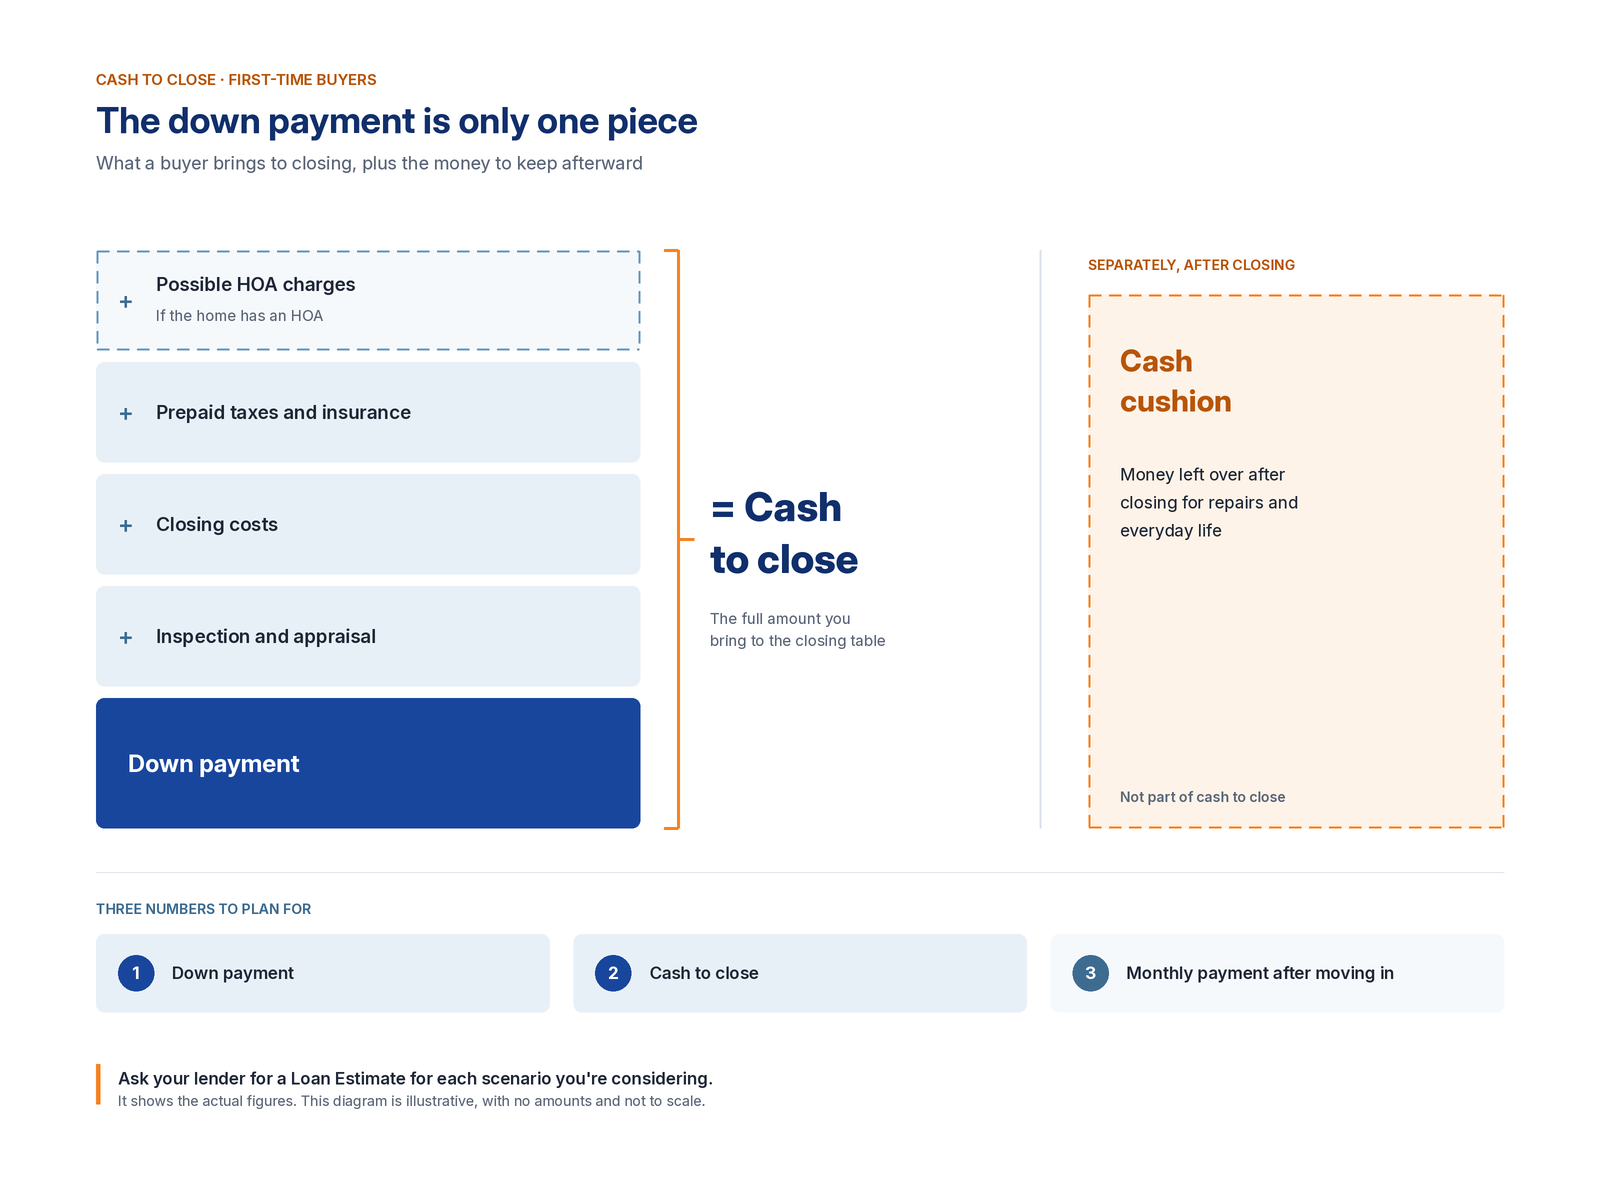
The practical step: ask your lender for a Loan Estimate for each scenario you're considering.
What's the trade-off of putting less down?
You borrow more, and you'll usually pay for mortgage insurance.
"A lower down payment can mean a bigger loan and possibly mortgage insurance, depending on the program," Caleb said. That doesn't make a small down payment a bad idea. Fannie Mae, for example, advertises reduced mortgage insurance on HomeReady loans that can be canceled later, with restrictions. It just means the monthly payment, not the down payment, is where the real comparison happens.
Rates matter here, too. Freddie Mac's national 30-year average was 7.32% as of Oct. 22, so build your scenarios on your lender's current quote, not a headline.
"So I ask buyers to have their lender compare scenarios in writing," Caleb said. What he doesn't want is the opposite extreme: "I wouldn't want somebody to use every dollar of savings simply to hit a round percentage."
Why does a cash cushion matter so much?
Because buying a home rarely goes exactly to plan.
Caleb worked with buyers renting in Newnan, careful savers focused on a manageable monthly budget. They found a three-bedroom home listed at $399,000 and went under contract at $396,000.
Then the appraisal came in at $386,000.
That gap worried them. Would they suddenly need to bring thousands more to closing? Caleb walked them through which number was which: the asking price, the contract price and the appraised value.
The lender handled the appraisal review, and the value didn't change. So our team went back to the seller's side, and the seller agreed to come down partway, to $389,000, still $3,000 above the appraisal. The buyers talked it through with their lender, decided the revised deal worked, and closed Aug. 14, 2026.
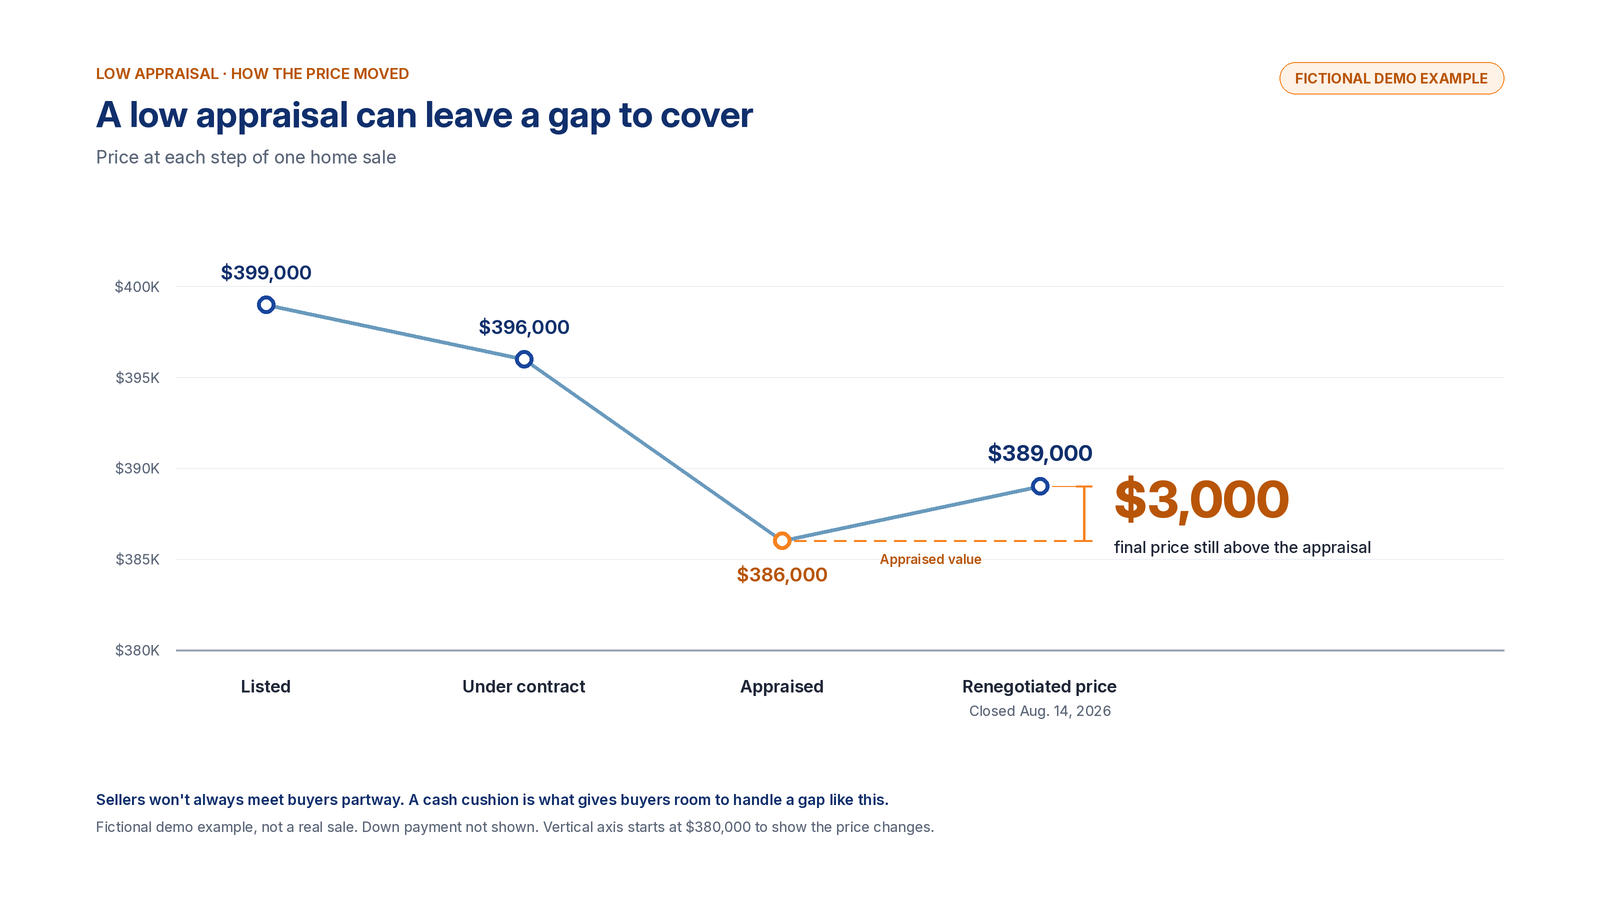
Caleb is careful not to read too much into this story. Sellers won't always meet buyers partway, and the story doesn't tell you what these buyers put down. "It's really a story about why buying with a safety cushion matters," he said. Money left in the bank after the down payment is what gives you room to handle a surprise like this one.
What should I ask about Georgia Dream and builder incentives?
Start with the question Caleb tells every buyer to ask a lender: "Do I actually qualify, and what will this cost in total?"
Georgia Dream is the state's homebuyer program, run by the Georgia Department of Community Affairs. Its down-payment assistance can help eligible buyers with the down payment and closing costs:
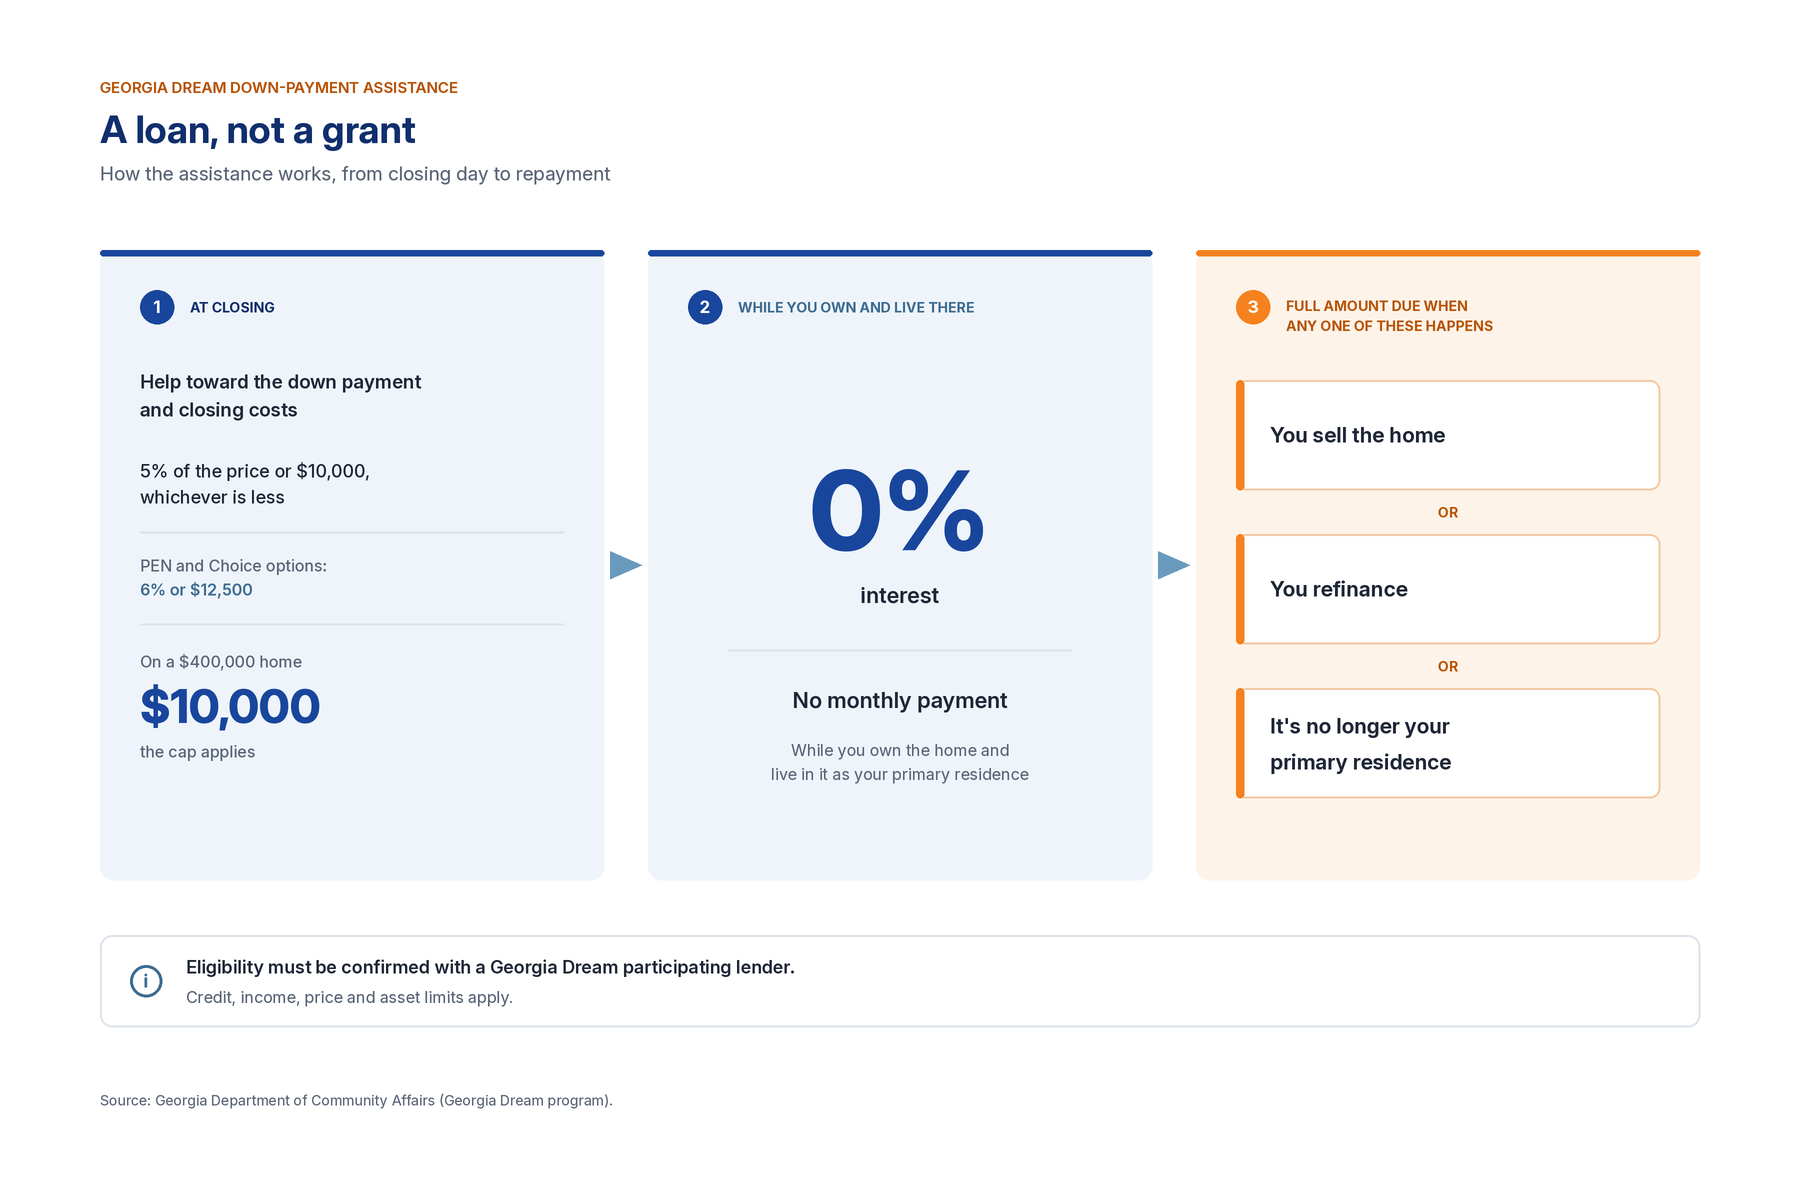
- How much: 5% of the purchase price or $10,000, whichever is less. Protectors, educators, health care workers and active military (the PEN option), and households with a member who has a disability (the Choice option), can receive 6% or $12,500. On a $400,000 home, the $10,000 cap applies.
- It's a loan, not a grant. The assistance is "a 0% interest loan with no monthly payment," the program explains. It's due when you sell, refinance or no longer live in the home as your primary residence.
- Requirements: at least $1,000 of your own money or documented gift funds, a credit score of at least 640, and a homebuyer education course.
- Limits for Coweta County: a $625,000 maximum sales price and household income up to $137,555 for one or two people or $158,188 for three or more. Your cash and other liquid assets after closing can't exceed $20,000 or 20% of the sales price, whichever is greater.
- Who qualifies as "first-time": first-time buyers, anyone who hasn't owned a home in the past three years, or buyers purchasing in certain designated areas.
The next step is a Georgia Dream participating lender; the state's line is 800-359-4663.
Fannie Mae's options work differently. HomeReady is aimed at lower-income borrowers, with an income limit of 80% of the area median income, and you don't have to be a first-time buyer. Its standard 97% option has no income limit but requires at least one first-time buyer on the loan.
Builder incentives deserve a close look, too. "With builder incentives, ask whether the attractive rate lasts for the entire loan or only the first year or two," Caleb said. Ask whether you have to use a preferred lender or close by a certain date. "Compare the whole payment and cash required under each offer, not just the advertised headline."
He's also clear about roles. "I can help buyers ask better property and contract questions, but I don't replace their loan officer."
Should I just wait until I've saved 20%?
Maybe. Just make it a choice, not a myth.
"I'd say there's no need to rush, but let's make sure waiting is a choice based on your actual options," Caleb said. His approach:
- Start with a comfortable monthly budget that includes taxes, insurance and maintenance.
- Ask a lender to show what 5%, 10% and 20% down would look like if you qualify.
- Keep a sensible emergency fund, whatever you put down.
If a smaller down payment still leaves you a stable plan, you may not need to wait as long as you thought. "If the budget's too tight, saving longer is sensible."
Most first-time buyers fund their down payment from personal savings (59%), with others drawing on financial assets such as a 401(k) (26%) or gifts or loans from family and friends (22%), according to NAR.
Whatever the source, Caleb's priority stays the same: "I care much more about whether a buyer will feel secure in the house than about whether they've reached some arbitrary down-payment number."
Key takeaways
- 20% isn't required. Qualified buyers may put down as little as 3% to 3.5%.
- Plan for three numbers: down payment, cash to close and monthly payment.
- Less down means a bigger loan and often mortgage insurance. Compare scenarios in writing.
- Georgia Dream assistance is a 0% loan, repaid when you sell, refinance or move out.
- Keep a cushion after closing.
- Waiting is fine when it's a choice, not a myth.
Recent Transactions From Our Team
Our agents help buyers across Newnan and Sharpsburg compare builder offers, follow up on inspections and keep closings on track. Here are a few of our recent buyer closings, along with feedback from the clients we helped.
Newnan
[DEMO] 303 Demo Lantern Walk, Newnan Listed: $389,000 · Sold: $382,000 · Closed: Oct. 6, 2026
"Caleb helped us look at what the promotion actually covered instead of just subtracting the advertised amount from the price." — Taylor Bennett
[DEMO] 1114 Demo Signal Ridge, Newnan Listed: $418,000 · Sold: $415,000 · Closed: Aug. 28, 2026
"He helped us request an address-specific check and understand the installation timeline." — Rowan Price
[DEMO] 306 Demo Foundry Crossing, Newnan Listed: $429,000 · Sold: $429,000 · Closed: July 2, 2026
"Caleb helped coordinate with the inspector, builder, and lender so we knew what needed to happen." — Harper Reed
Sharpsburg
[DEMO] 1215 Demo Fieldstone Hollow, Sharpsburg Listed: $439,000 · Sold: $432,000 · Closed: Sept. 4, 2026
"When we had questions about the well water, she helped us get testing and specialist input rather than guessing." — Jordan Walker
Meet our team
Caleb Brooks helps buyers in Newnan and Sharpsburg compare homes, contracts and builder offers. Avery Collins guides buyers through showings, inspections and offers. Morgan Bennett helps sellers price, prepare and document their homes.
Wondering what you'd actually need to buy your first home in Newnan or Sharpsburg? We'd be glad to help. Reach out to our team at Sharpsburg Realty Experts, and we'll help you prepare the right questions for a lender and look at homes that fit the budget you're comfortable with.