Sharpsburg
Mortgage Rates Dipped to 7.32%: Is Late Fall a Buying Window in Sharpsburg?
By the Sharpsburg Realty Experts Media Team
Demo content: not for publication. The agent interviews, agent profiles, client stories, transactions and client reviews in this test article are fictional demo records. They don't describe real people, real sales or real testimonials. The rate, market and news data cited are real and linked to their sources.
For the first time in two months, mortgage rates went down instead of up.
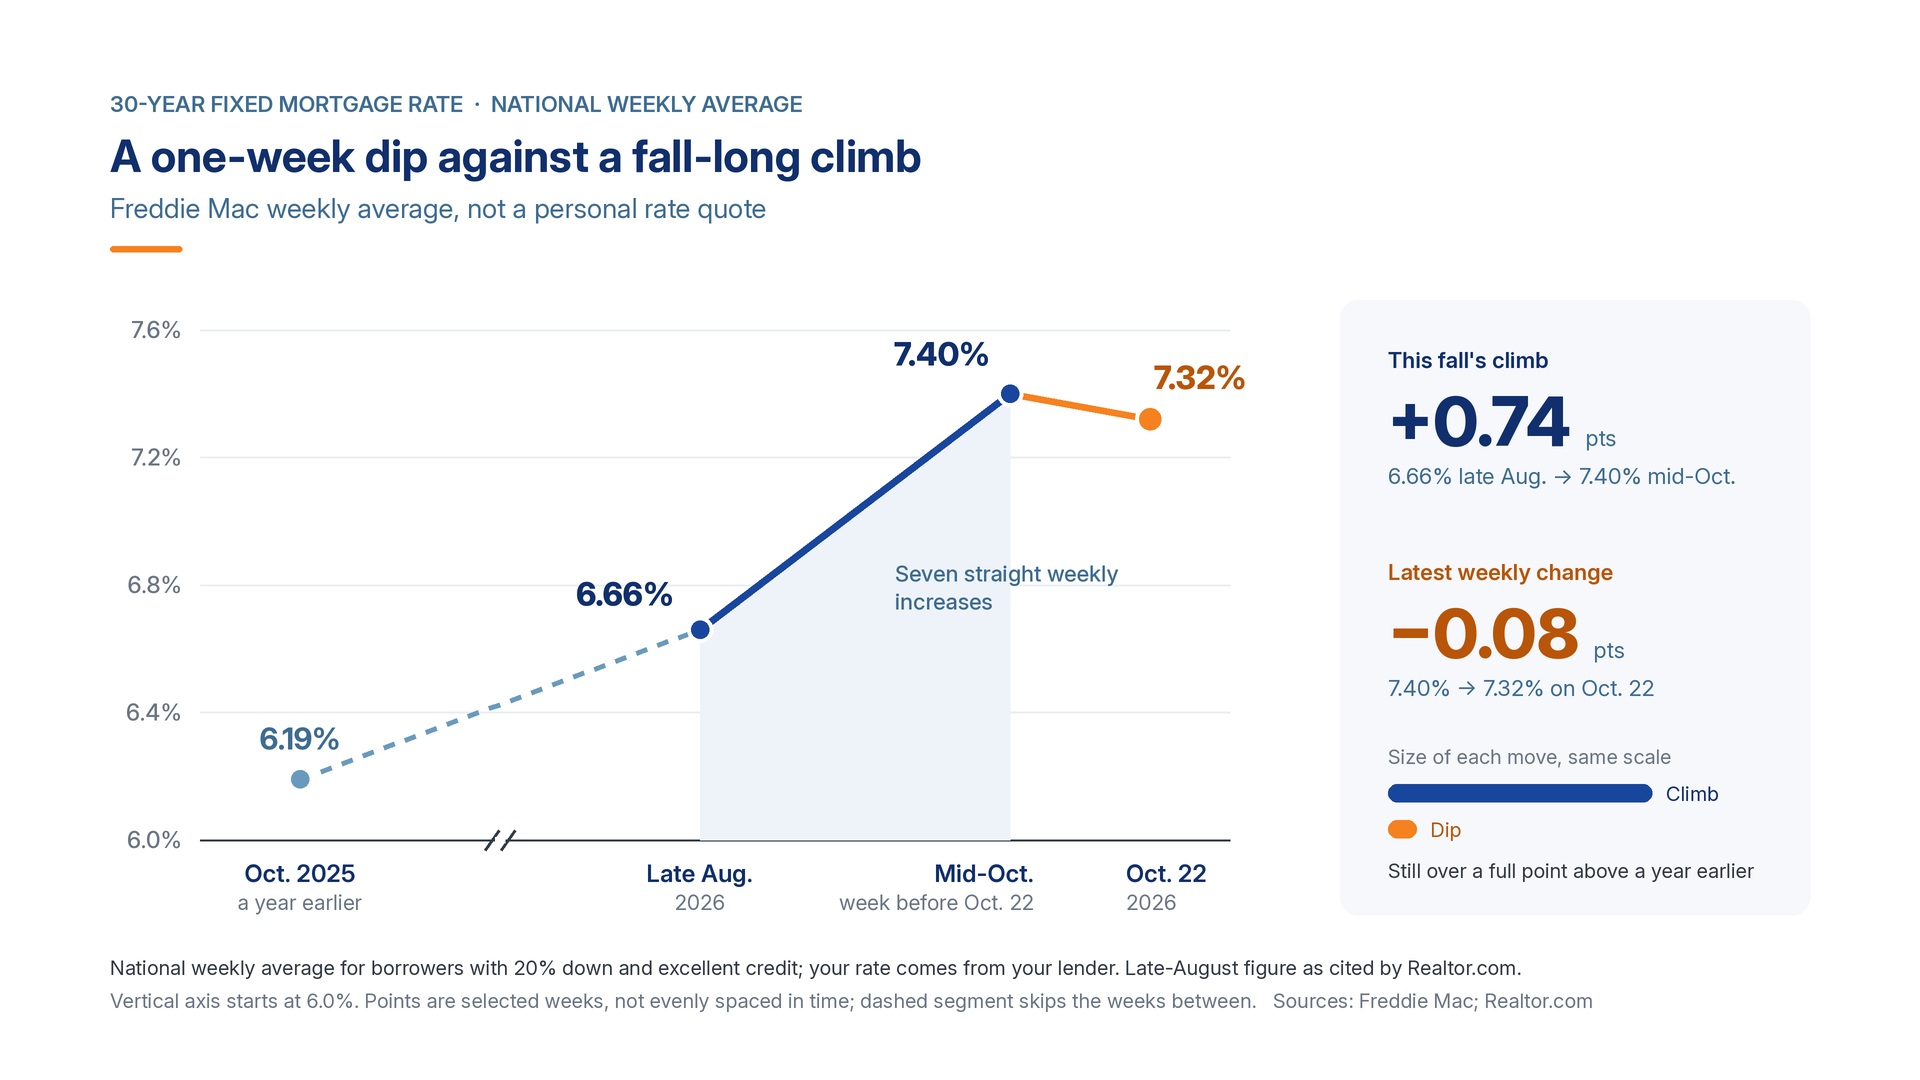
Freddie Mac's 30-year average eased to 7.32% on Oct. 22, from 7.40% a week earlier. The same week, reports showed home contracts falling sharply across the country and in metro Atlanta. Put those together and it sounds like an opening: cheaper money, fewer rivals.
If you've been waiting on the sidelines in Sharpsburg, the question is whether to step back in. So our media team checked the new rate and contract reports against Coweta County's own numbers, then asked Avery Collins, one of our Sharpsburg buyer specialists, what she's telling buyers right now. Our short answer: more time and more room to ask, yes. Cheap money, no.
Does the rate dip change what I can afford?
Only a little, and that's worth knowing before you call it a turning point.
The drop was 0.08 of a point. The average is still more than a full point above where it was a year ago, 6.19%. And it follows seven straight weekly increases. Realtor.com estimates that the climb from 6.66% in late August to 7.4% on Oct. 8 cost buyers about 7.2% of their purchasing power. As senior economist Jake Krimmel put it, "today's modest decline does not put much of a dent in this fall's surge."
Avery's buyers noticed the headline, but it didn't set off a rush of offers. One sent it to her with a simple question: "Does this change what I can afford?" Her answer was to have the lender rerun the actual payment with today's options. "A small movement can get someone's attention without changing their budget very much," she said. "And I wouldn't tell anyone that a one-week dip means rates have turned a corner."
Keep in mind that Freddie Mac's figure is a national weekly average for borrowers putting 20% down with excellent credit. Your rate comes from your lender.
With fewer contracts, are Sharpsburg homes just sitting?
Some are. But the local slowdown is much milder than the metro headline suggests.
The pattern changes depending on how far out you zoom:
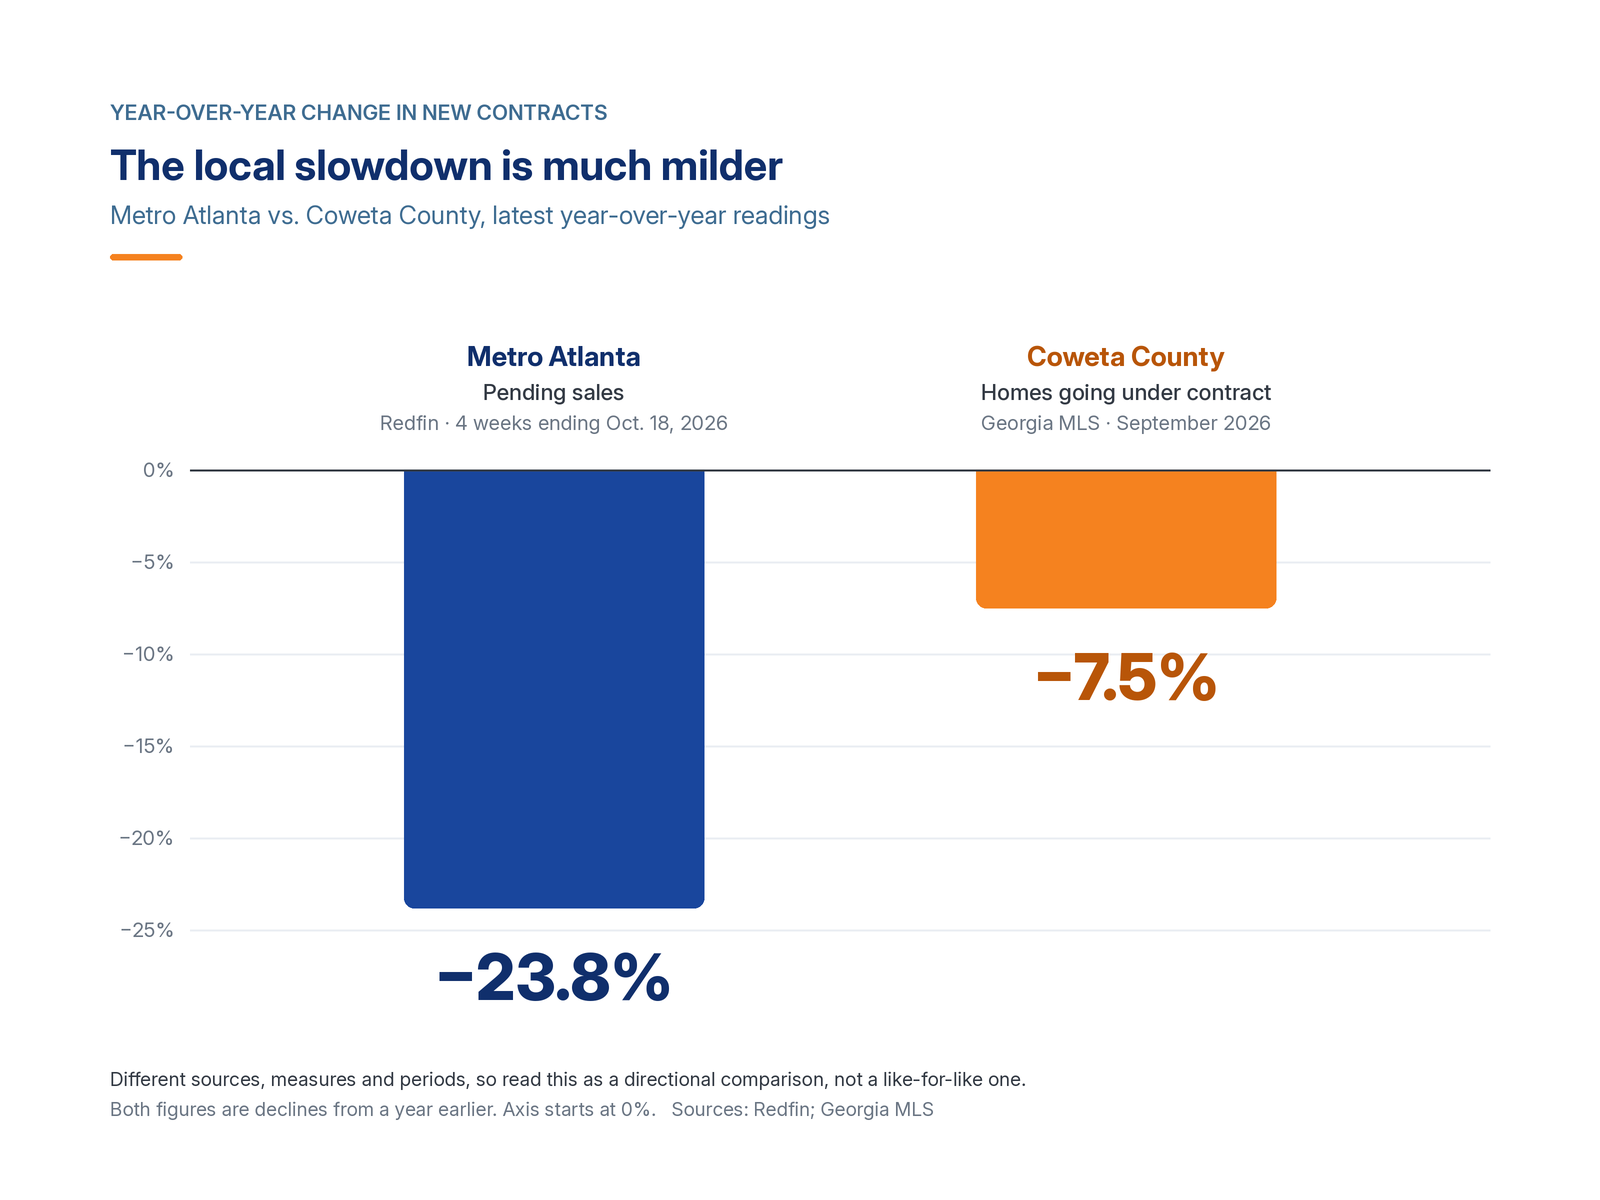
- Metro Atlanta saw one of the steepest drops in the country. Pending sales fell 23.8% from a year earlier in the four weeks ending Oct. 18, and new listings fell 24.2%, according to Redfin.
- Coweta County cooled far less. Georgia MLS counted 160 homes going under contract in September, down 7.5% from a year earlier, while sales rose 7.6% to 183.
- ZIP code 30277 is moving more slowly. Over the three months ending in September, homes took a median of 55 days to sell, up from 45, Redfin reports.
So the slowdown is real here, just not the same one the metro numbers describe.
That matches what Avery sees at showings. "I'd describe it as a more thoughtful pace," she said. Buyers are willing to see a house twice, ask questions and compare it with another option before deciding.
Not every listing feels that slowdown, though. "A well-kept house with the right layout and a realistic price can still get attention," while homes with awkward floor plans or a lot of deferred maintenance tend to sit longer. "That's why I don't just point at the Atlanta numbers and call every Sharpsburg street a buyer's market."
Is it smart to hold off?
For some buyers, yes, and that can be a strong decision.
The payment is the sticking point. Nationally, the median monthly housing payment reached $2,796 at a 7.4% rate in Redfin's latest report, up 10.4% from a year earlier.
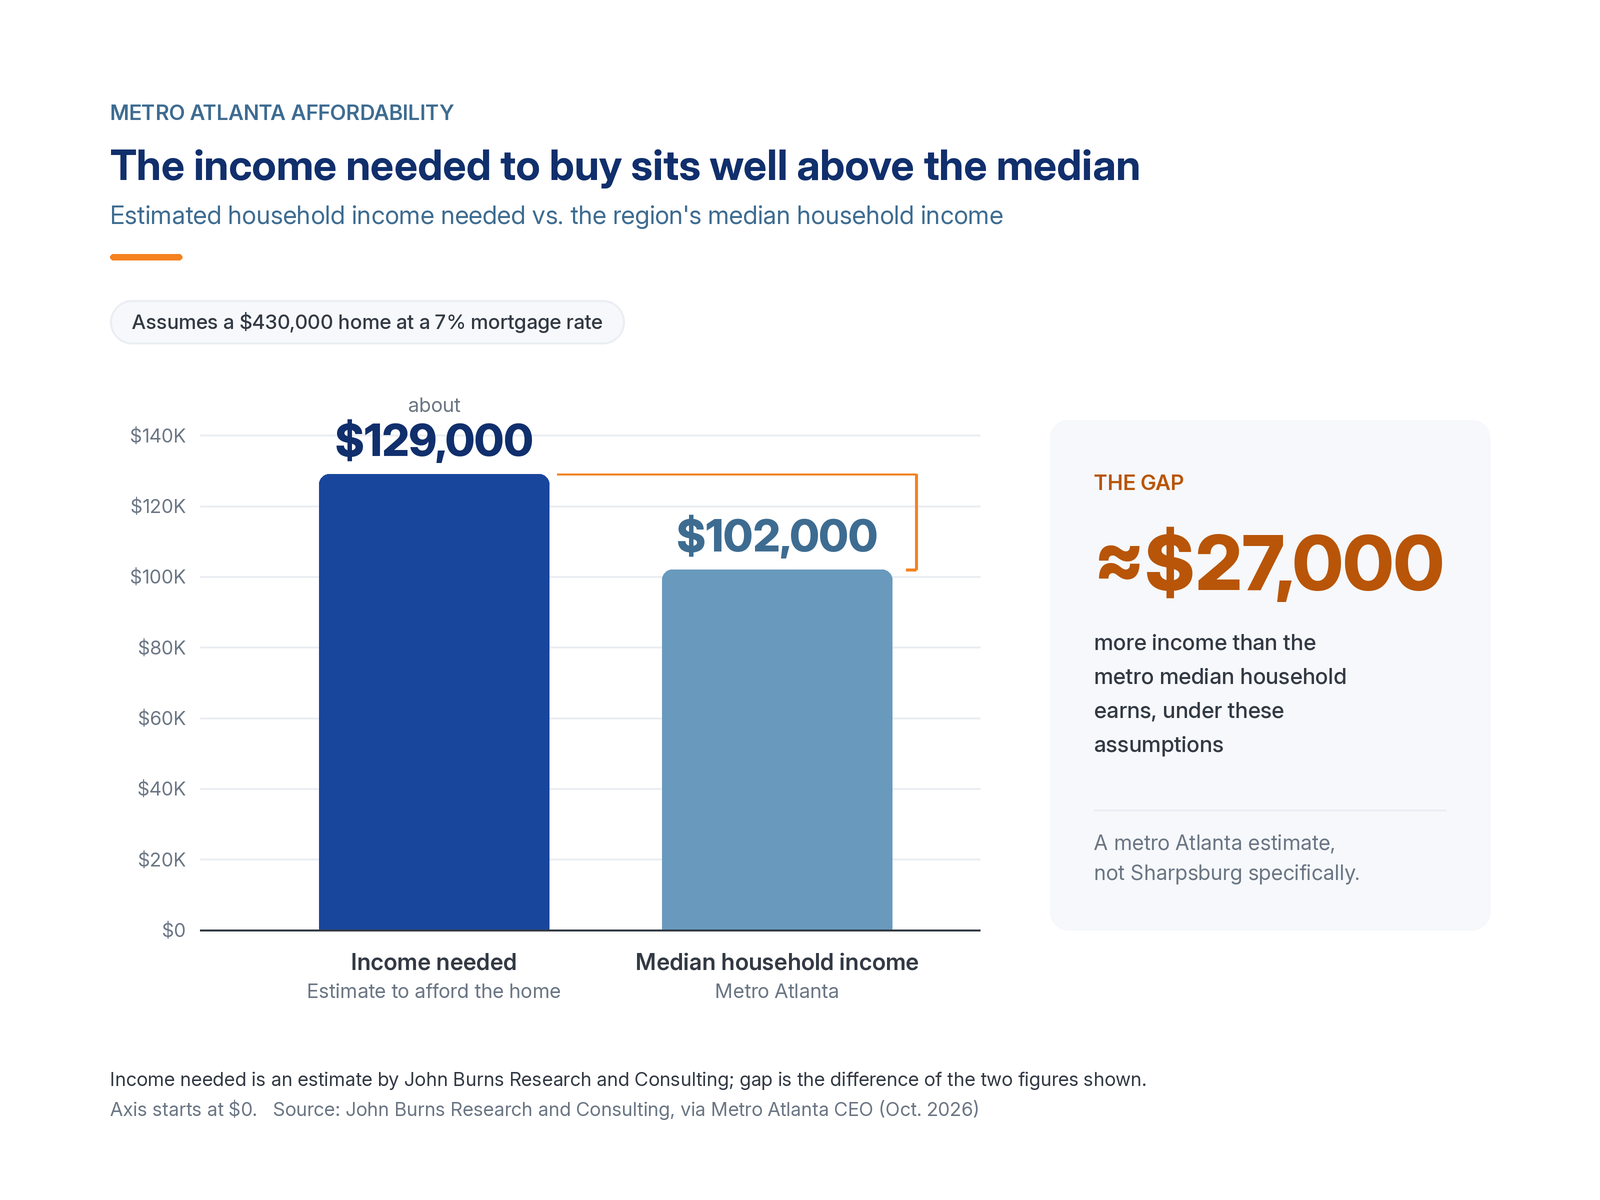
Closer to home, the math is just as tight. In metro Atlanta, John Burns Research and Consulting estimates a household needs about $129,000 in income to afford a $430,000 home at 7%, well above the region's $102,000 median household income, Metro Atlanta CEO reported.
That pressure shows up in the contract numbers. "Buyers and sellers may simply be holding back until mortgage rates move favorably," NAR chief economist Lawrence Yun said as pending home sales fell 11.3% year over year in September.
Avery has watched buyers adjust their timelines once a lender laid out the full monthly cost, with taxes, insurance and older-home repairs added in. One couple compared the numbers and decided to keep renting while they built a bigger cushion. "That wasn't a failure," she said. "They'd rather wait than get into a payment that feels tight every month."
She's also careful not to promise a future rescue. "I wouldn't promise that rates will fall later or that refinancing will fix a payment they're uncomfortable with today."
What does this market look like in a real purchase?
It often looks like time: time to investigate a problem properly rather than rush past it.
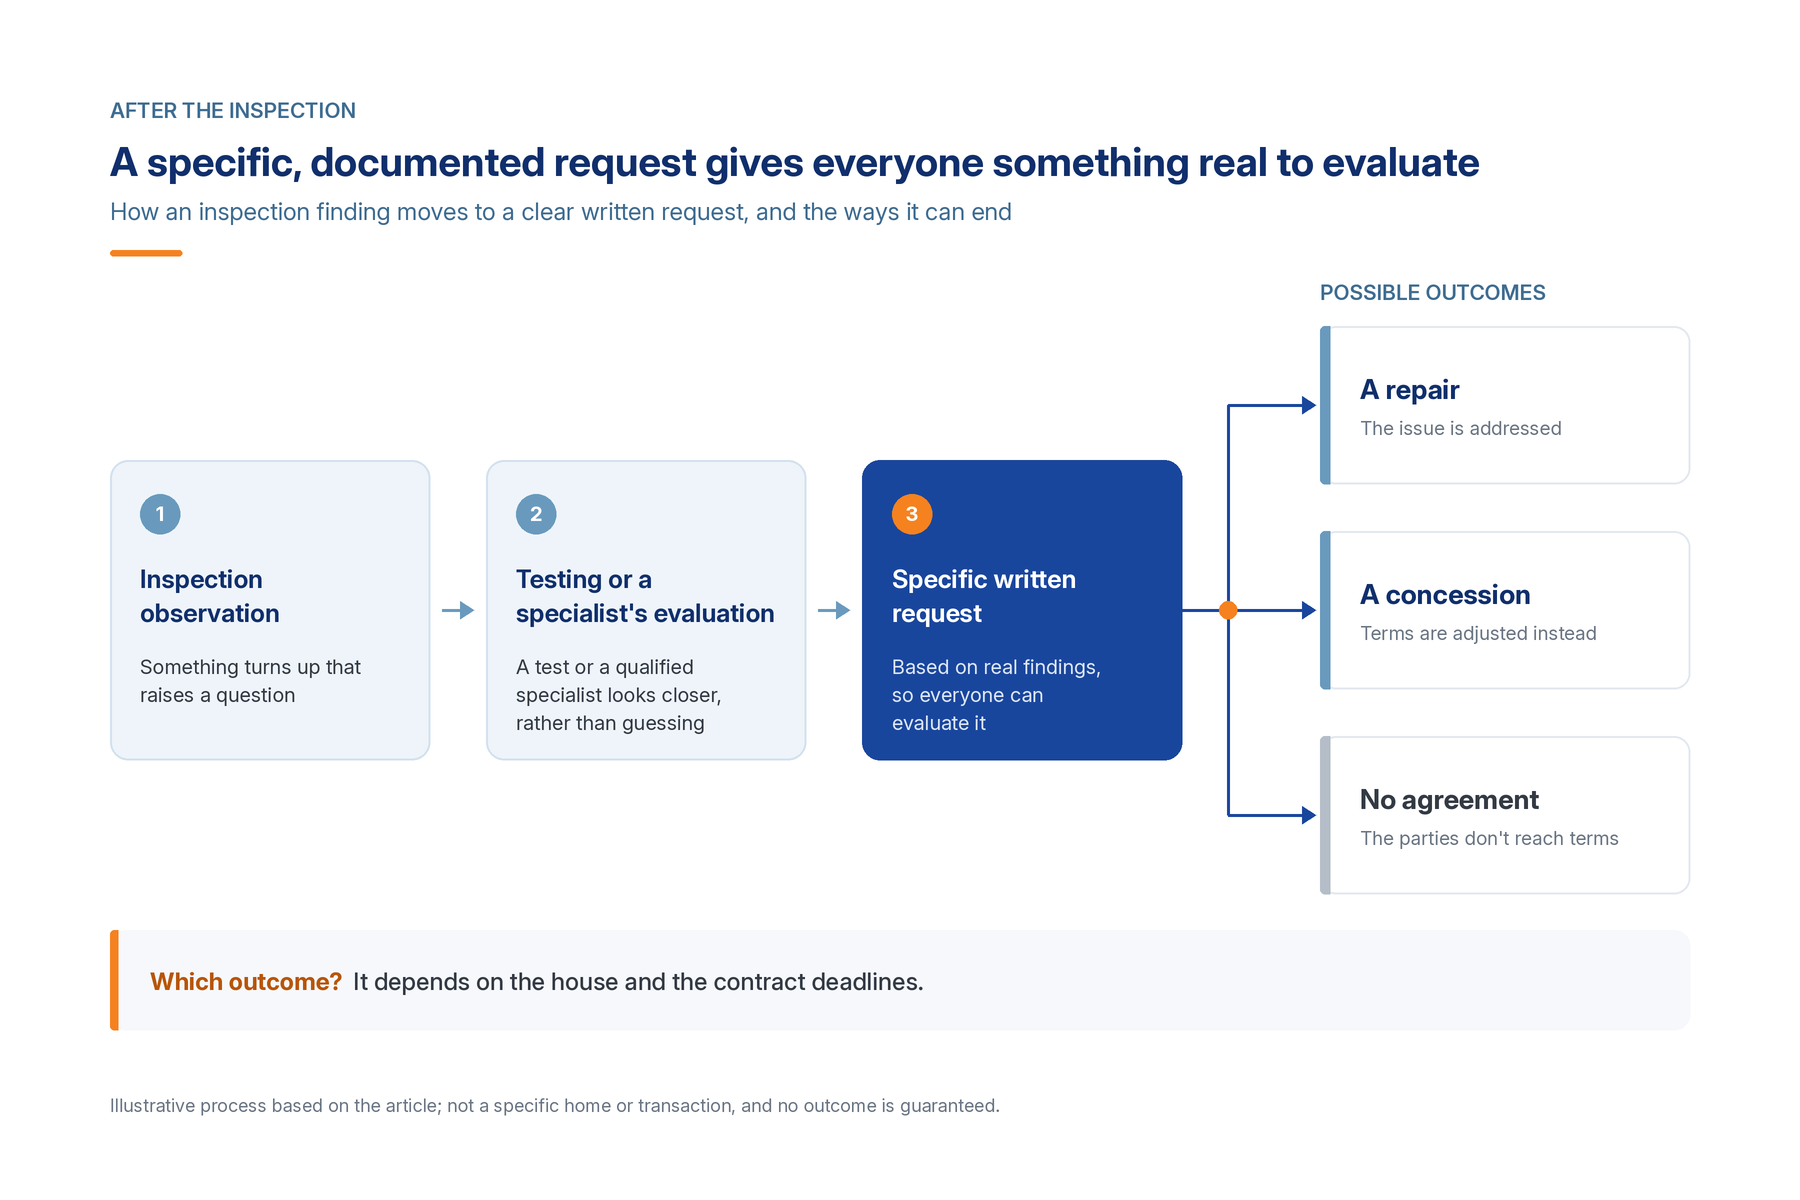
Avery's clients found a single-story Sharpsburg home with a larger yard, listed at $439,000, and agreed on $432,000. During inspection, staining showed up at some fixtures, raising questions about the private well.
"We didn't guess from the stain," Avery said. We arranged a lab test and an evaluation by a well contractor, which pointed to a specific treatment system. With real findings in hand, the request was clear, and the seller paid $1,850 to install it. The price stayed where it had been negotiated, and the sale closed Sept. 4, 2026.
Avery credits the approach, not the market slowdown, for that result: "a written, specific request gives everybody something real to evaluate." Depending on the house and the contract deadlines, that request might end in a repair, a concession or no agreement at all. "The point isn't that buyers can demand whatever they want."
Should I expect price cuts or seller concessions?
Expect conversations, not guarantees.
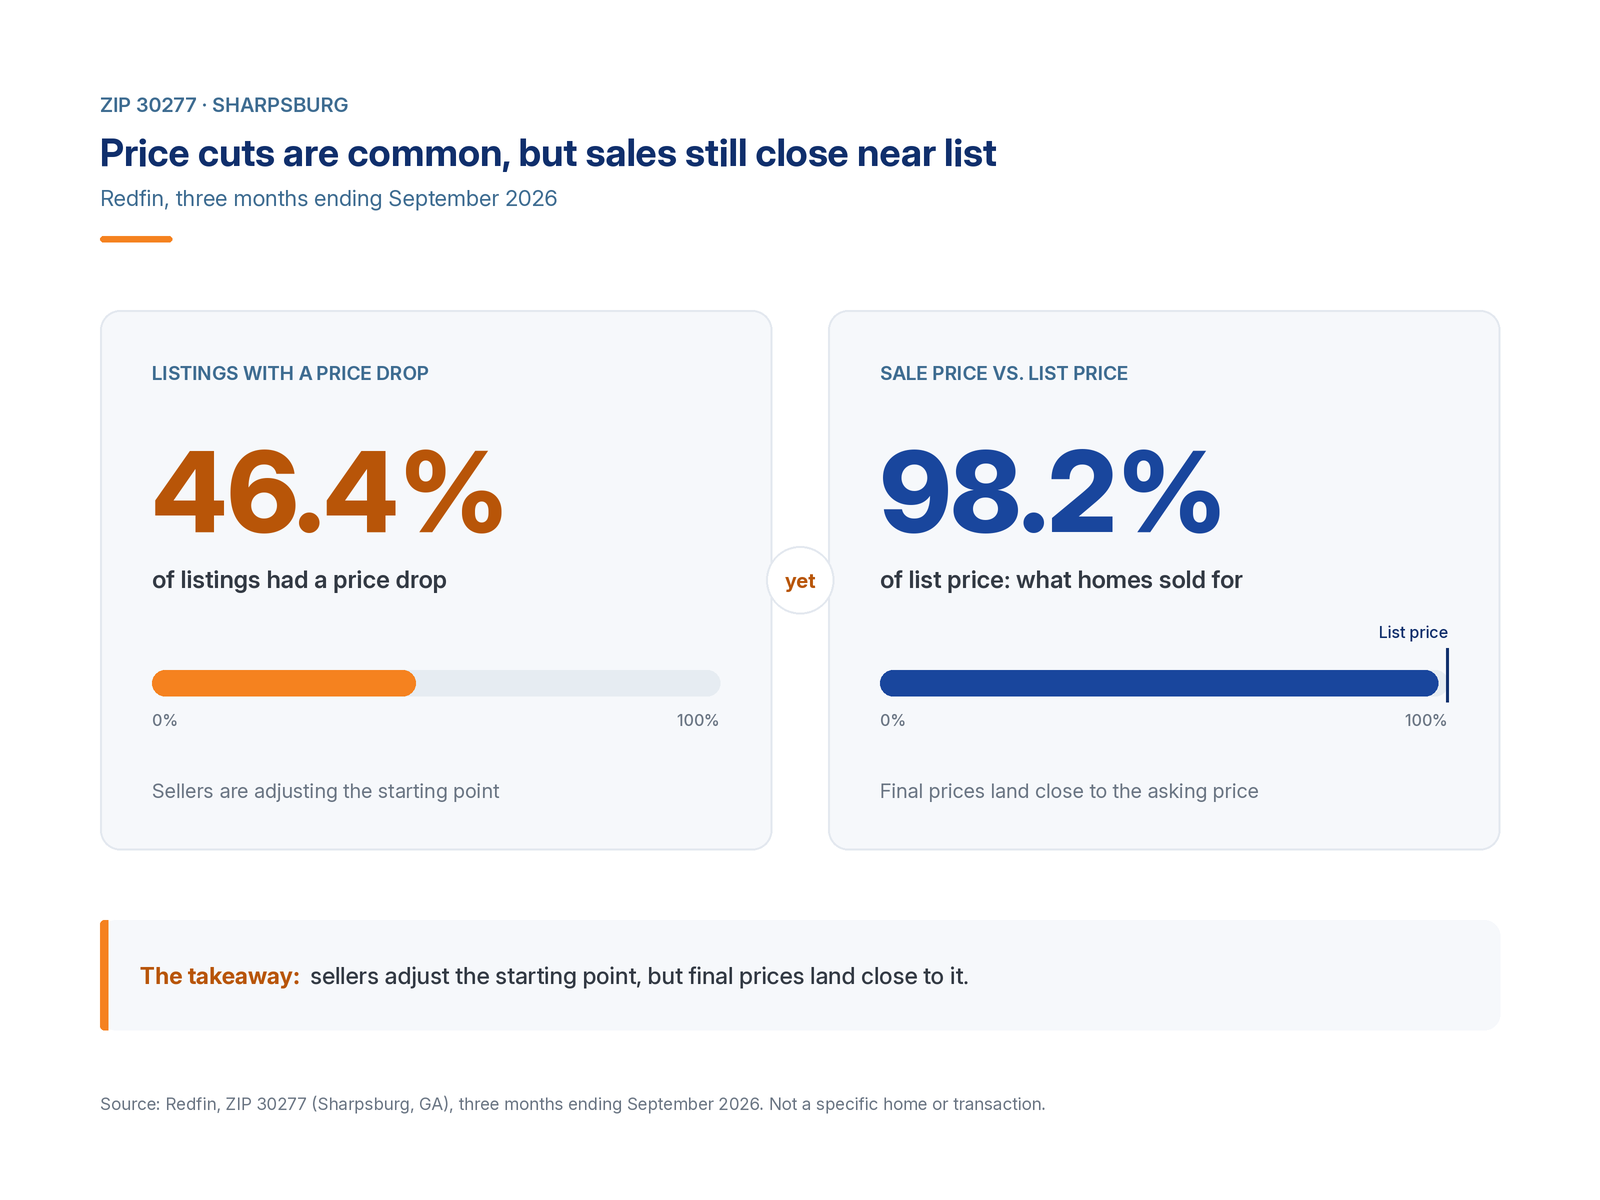
Price reductions have become common locally. In ZIP 30277, 46.4% of listings had a price drop over the three months ending in September, yet homes still sold for 98.2% of list price, according to Redfin. In other words, sellers are adjusting their starting point, but final prices are landing close to it.
Avery sees more openness to discussing terms. Some sellers lower an asking price after the market tells them it was too high. Others would rather help with closing costs, depending on what the buyer needs and the lender allows. Sometimes the answer is no. And she keeps the two tools separate: "A price reduction that happened before the contract is not the same as a concession negotiated during inspection."
Our listing specialist Morgan Bennett used both this spring. One Sharpsburg seller lowered the asking price and, once a buyer came in, also agreed to a separate $3,000 closing-cost contribution. A price cut, Avery adds, isn't proof of a hidden problem. Compare the home with similar sold properties and look closely at condition.
How should I prepare to make an offer now?
Get your numbers and priorities ready before you fall for a house. Avery's list:
- A property-specific payment estimate from your lender, including taxes, insurance, any dues and room for maintenance, not just a preapproval amount.
- Clear priorities. Is a one-story layout a must or a preference? How much work can you realistically take on?
- Your deadlines. Know your inspection and financing windows. If a roof or drainage concern comes up, bring in a qualified specialist rather than asking your agent to diagnose it.
- Comparable sales to back up your offer.
It also pays to compare whole deals. Our colleague Caleb Brooks recently helped Newnan buyers weigh a resale with a $7,000 seller closing-cost contribution against a bigger advertised builder incentive tied to a preferred lender. Once their lender walked through both, the bigger number wasn't the obvious winner, and they chose the resale.
Just don't overplay the market. "Slower doesn't mean unlimited bargaining power."
So should I buy now or wait?
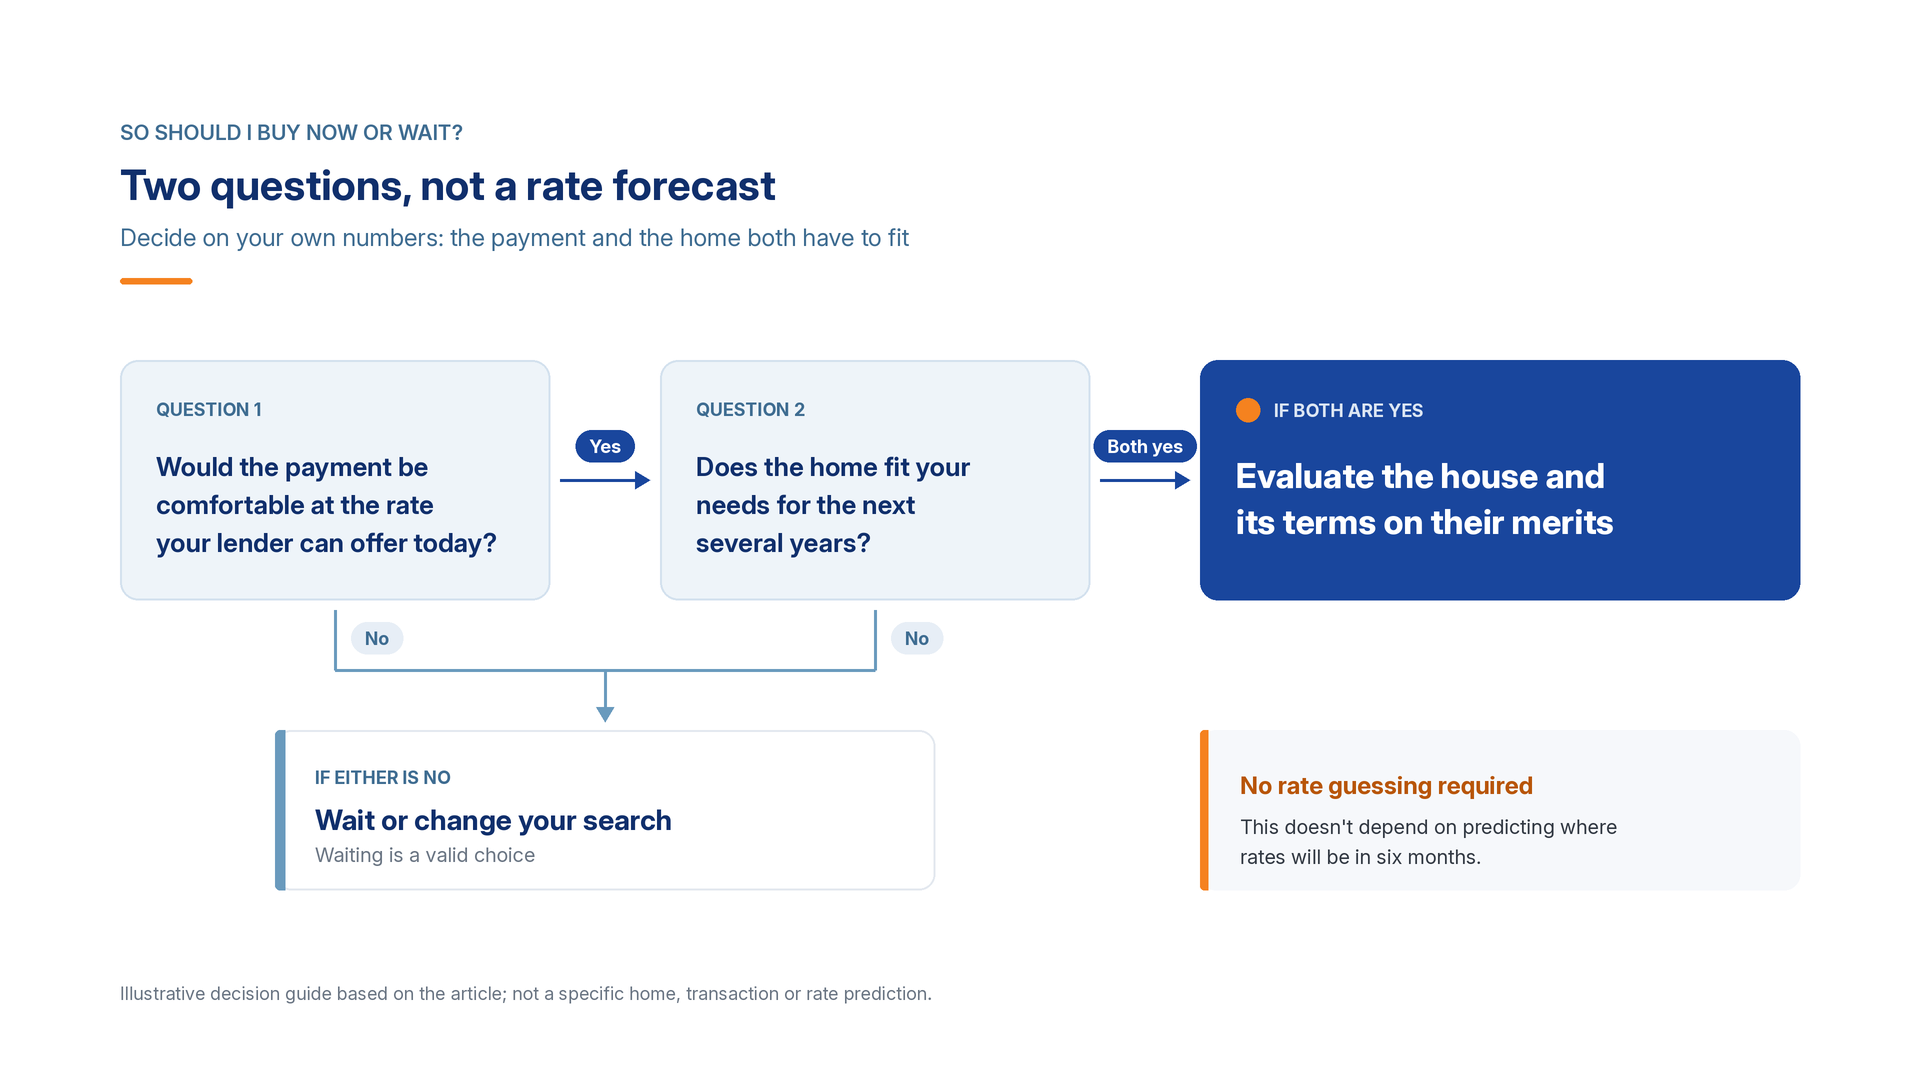
Avery boils it down to two questions:
- Would the payment be comfortable at the rate your lender can offer today?
- Does the home fit your needs for the next several years?
If either answer is no, waiting or changing your search makes sense. If both are yes, we evaluate the house and its terms on their merits, without trying to guess where rates will be in six months.
Even economists can't say for sure. Yun thinks rates "could be topping out," but he calls the inflation picture tied to energy prices "highly uncertain." That's one more reason to decide on your own numbers.
"The one thing I wouldn't want is a buyer making a rushed decision because a headline said there's a buying window this week," Avery said. Her bottom line: "Lower competition and higher borrowing costs can both be true."
Key takeaways
- 7.32% is a dip, not a turn. It's still well above last year's 6.19%.
- The local slowdown is milder. Metro Atlanta pending sales fell 23.8% year over year; Coweta's September contracts fell 7.5%.
- Start with a property-specific payment from your lender.
- Fewer rival buyers means more time to investigate, not unlimited leverage.
- Price cuts and concessions are different tools.
- Buy when the payment and the home both fit. Waiting is a valid choice.
Recent Transactions From Our Team
Our agents work with buyers and sellers across Sharpsburg and Newnan, from comparing financing offers and coordinating repairs to keeping contingencies and closing dates on track. Here are a few of our recent local closings, along with feedback from the clients we helped.
[DEMO] 303 Demo Lantern Walk, Newnan
Listed: $389,000 · Sold: $382,000 · Closed: Oct. 6, 2026
"He also encouraged us to compare the houses themselves, not just the financing headline."
— Taylor Bennett
[DEMO] 1518 Demo Lanterncrest Road, Newnan
Listed: $469,000 · Sold: $463,000 · Closed: Oct. 2, 2026
"Caleb helped get the right people involved, and we waited for the repair and another walkthrough rather than ignoring the issue."
— Emery Turner
[DEMO] 1417 Demo Summerbranch Drive, Sharpsburg
Listed: $475,000 · Sold: $470,000 · Closed: Sept. 18, 2026
"It felt better to be straightforward with buyers than to create confusion later."
— Ellis Woods
[DEMO] 1114 Demo Signal Ridge, Newnan
Listed: $418,000 · Sold: $415,000 · Closed: Aug. 28, 2026
"He helped us request an address-specific check and understand the installation timeline."
— Rowan Price
[DEMO] 1013 Demo Pinebasket Court, Sharpsburg
Listed: $499,000 · Sold: $495,000 · Closed: Aug. 21, 2026
"Morgan helped keep track of the buyer's home-sale contingency and the various closing dates."
— Jamie Rivers
Meet our team
Avery Collins helps Sharpsburg buyers build offers and requests around real payment numbers and specialist findings. Morgan Bennett guides sellers on pricing, preparation and terms. Caleb Brooks works with Newnan buyers comparing resales, new construction and incentive offers.
Wondering whether this fall makes sense for you? We'd be glad to help. Reach out to our team at Sharpsburg Realty Experts, and we'll help you line up a property-specific payment with your lender and look at what's actually selling near you, with no pressure to rush.